
Downloaded from hlayiso.com
testpapers.co.za
Skip to content
View all





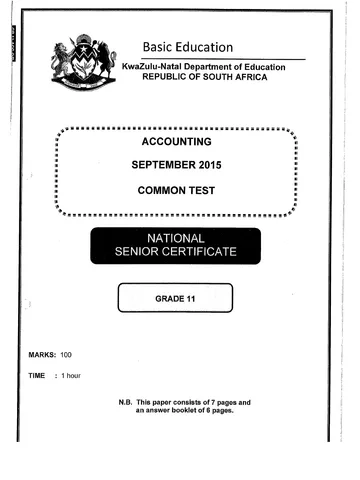
Accounting Grade 11 September Test 2015 Paper & Memo
Grade 11 Accounting question paper and memo from the September Test 2015, 12 pages. Read online or get the free PDF download.
Accounting · Grade 11 · September Test · 2015. Question paper and memorandum, 12 pages. Read online or download the PDF.
- Subject
- Accounting
- Grade
- Grade 11
- Document type
- Question paper and memo
- Year
- 2015
- Exam period
- September Test
- Curriculum
- CAPS
- Pages
- 12
- File size
- 660.0 KB
Free to read online, no sign-up needed
Loading document…
Loading document…
1 of 12
Document textSearch extracted text and jump to a page.
Downloaded from hlayiso.com
Accounting (Grade 11) 2 Common Test September 2015
NSC
INSTRUCTIONS AND INFORMATION
Read the following instructions and be sure to follow them carefully:
1. This question paper consists of 7 pages.
2. A special ANSWER BOOK consisting of 5 pages is provided in which to answer
all the questions.
3. Answer ALL the questions.
4, Workings must be shown in brackets in order to earn part marks.
5. Non-programmable calculators may be used.
6. You may use dark pencil or black / blue pen to answer the questions.
7, Marks will be deducted for missing details and foreign entries.
8. Use the information in the table below as a guide when answering the question paper:
Question 1; 23 Marks, 14 Minutes
The topic of this question is: Content:
. e Interpretation of Work-in-Progress Account
Cost Accounting e Break even point
Question 2: 52 Marks, 31 Minutes
The topic of this question is: Content:
Budgetin e Debtors Collection Schedule
geting « Projected Income Statement
Question 3: 25 Marks, 15 Minutes
The topic of this question is: Content:
e Purchases Account
Inventory Systems * Calculation of Sales and Cost of Sales
Copyright Reserved Please Turn Over
Downloaded from hlayiso.com
Accounting (Grade 11) 3 Common Test September 2015
‘ NSC
QUESTION 1 (23 Marks, 14 Minutes)
COST ACCOUNTING
1.1. General Ledger and Interpretation
Required
Study the Work-in-Progress Stock account in the General Ledger of Themba’s Wooden
Tables and answer the questions that follow:
1.1.1 In which section of the General Ledger will this account be found? (1)
1.1.2 Identify TWO items that can be included in each of the following amounts in the
Work-in-Progress Stock account:
(3 a) R112 300. (2)
b) R210 600. (2)
1.1.3. Themba currently employs one supervisor and 3 carpenters to make the tables. (4)
Identify which of his employees are considered to be direct labour and indirect
labour. Explain your reasoning by giving an example of the type of work each
employee will be completing.
1.1.4 If this business made 160 wooden tables and sold each table for R4 350, calculate
the following:
a) The cost price per table. (2)
b) The mark up percentage applied by Themba’s Tables. (4)
Information:
Work in Progress Stock
er 2015 Finished Goods
March 1 | Balance 96 800 Feb 28 Stock 464 000
are 28 | Direct Labour Cost | 137 800 Balance 93 500
racy Overhead 412 300
‘ost _
Raw Materials Cost | 210 600
557 500 557 500
2015
March 1 | Balance 93 500
Copyright Reserved Please Turh Over
Downloaded from hlayiso.com
Accounting (Grade. 11) 4 Common Test September 2015
NSC
1.2 Break Even Point
Billy Bob’s Beds produced and sold 3 950 single beds for the year ended 31 August
2015. The following information was extracted from their books:
Information:
Sales R4.740 000
Variable Costs R2 646 500
Fixed Costs R713 500
1.2.1 Calculate the break-even point for the year ended 31 August 2015. ( RS)
4.2.2 Should Billy Bob’s Beds be satisfied with the number of single beds that were made (3)
during the year ended 31 August 2015? Explain.
Copyright Reserved Please Turn Over
Downloaded from hlayiso.com
Accounting (Grade 11) é Common Test September 2015
NS
QUESTION 2 (52 Marks, 31 Minutes)
BUDGETING
Required:
2.1 Explain the difference between a Projected Income Statement and a Cash Budget. (4)
2.2 Complete the following for September to November 2015. (Some amounts have been
entered for you.):
2.2.1 Debtors Collection Schedule. (9)
2.2.2 Projected Income Statement (39)
Information
; Green Tree Stores Income Statement for the year ended 31 August 2015
3 Sales 1600 000
Cost of Sales (1 000 000)
Gross Profit 600 000
Other Operating Income 73 600
Rent Income 56 800
Commission Income 16 800
Gross Operating Income 673 600
Operating Expenses (456 500)
Salaries 240 000
Advertising 30 000
Bad Debts 20 000
Depreciation 48 600
. Sundry Expenses 117 900
() Operating Profit 217 100
Interest Expense (on Loan) (19 200)
Net Profit for the year 197 900
Copyright Reserved Please Turn Over
Downloaded from hlayiso.com
Accounting (Grade 41)
Additional Information
1.
6
NSC
Common Test September 2015
Sales (including forecasted sales) for the period 1 July 2014 to 30 November 2015 are
shown below:
July 2015 119 000 35 700 83 300
August 2015 127 000 38 100 88 900
September 2015 132 000 39 600 92 400
October 2015 136 000 40 800 95 200
November 2015 140 000 42 000 98 000
Credit Sales are expected to be collected as follows:
« 20% in transaction month to receive a 5% discount.
« 70% in the month after the transaction.
« 5% two months after the transaction.
e
5% irrecoverable and is written off two months after the transaction.
The current percentage mark up on cost will be maintained throughout the budget period.
« Anincrease in salaries becomes effective on 1 September each year. An increase of
8% has been budget for on 1 September 2015.
e The business currently has 3 employees earning the same monthly salary. From
1 November 2015, a fourth employee, who will earn the same salary, will be employed.
The monthly rental was increased by R800 on 1 October 2014. The business intends to
increase the tenants rent by R1 000 from 1 October 2015.
Green Tree Stores currently pays interest in their loan at.a rate of 8% per annum. The
capital portion of the loan remained unchanged during the previous financial year. The
business plans to increase this loan by R60 000 on 1 November 2015.
The business plans for dispose of unused equipment at a book value by the end of
September 2015. This will decrease the depreciation on equipment by R200 per month
from 1 October 2015. (Note that no assets were bought or sold during the financial year
ended 31 August 2015. Assets are depreciated on cost)
( ‘
Sundry expenses are estimated at R10 000 in September and thereafter to increase by 2%
per month.
Copyright Reserved
Please Turn Over
Downloaded from hlayiso.com
Accounting (Grade 11) 7 Common Test September 2015
NSC
QUESTION 3 (25 Marks, 15 Minutes)
INVENTORY SYSTEMS
Required:
Use the information provided below to complete the following for Peter’s Plumbing Suppliers for
the year ending 31 July 2015.
3.1. The Purchases account in the General Ledger, correctly closed off on 31 July 2015. (13)
3.2 Calculate the Cost of Sales, for the year ending 31 July 2015, using the periodic (7)
inventory system. (Show calculations in brackets so part marks can be awarded.)
i}
3.3 Calculation of the Gross Profit for the year ending 31 July 2015. (5)
Information:
Extract from the Trial balance on 1 July 2015:
Trading Stock (1 August 2014) 10 600
Purchases 450 000
Carriage on Purchases 6 500
Sales 710 000
( “ditional Information for July 2015:
e R117 000 stock was purchased during July 2015. One third of this was for
cash, the remainder was bought on credit.
e Peters Plumbing Suppliers was charged R600 for the transportation of stock
from the suppliers to their shop.
e Defective stock valued at R 5 100 was returned to Tool City, our creditor,
e The owner took stock worth R1 300 for personal use.
e Total sales for the month amounted to R53 600.
e According to a physical count, stock worth R12 400 was on hand on 31 July
2015.
TOTAL MARKS: [100]
Copyright Reserved
Downloaded from hlayiso.com
©
JaAQ WL aseaid paruasey 1yBukdod
¥ A006 Z
a%0S = OO X ————______
(,006 2 — pose ¥)
‘saige| S,equouy Aq paydde aBequaoied dn yew eu, = (q
77006 ZY = 091 / 000 vor |
“ejqe} sod eaud ysoo oy fe
:Buymoyjoy ayy ayeynayea.
‘OSE Pe 403 aIqe} YORS Pjos Pue SezIqGe} VEPOOM OL apeU SseuIsNg SIA PLL
id A saiger au} exew AjjeorsAyd jou
op 3nq euop Buleg si Nom 319 Yeu} uNsuS ai — plosuuadng | MOTT PeupUL
/SAIGE} OU] eye Alesiskyd Aayy—~ psuequedseg | — snogeq yoauig
“Bugajdwios aq jm daXojdusa yore yi0M Jo
ody ou jo ajdwexe ue Buia6 Aq Buluoseas sno ulejdxy ~snoqe| yesIpul pue
4Noge| 33e11p 3q 0} pasap}sucs ase seafojdura siy jo yoIyM AyUAp] “saiqey
8th eyeut 0} suajuaded ¢ pue oOs|AJadns auo SAojdua AQuauiris equieyt o'y"L
z 3809 sjeuazeul mes jea)Go} Auy
usin
SHEN
Peng,
PPOOM,
see
‘cogalzy =
Jaunjoepnuew
Zz 8/qe} & 104 asuadxe peaysaAo jeo!boj Auy
SIELE}EW 108|9U
anoge?) aupul
souemsuy Aiopes
sleusy Aiopes
/AOUIDEIS pue Jaye
eee eee
‘ooeziu fe
sunosoe y90}¢ ssesBorg-ul
HORA 24) Ul SuNOWE BuIMo}[O) OUR UI Pepnjou! oq UeD JEU} SUE OML AIMUEP] ZLL
Downloaded from hlayiso.com
el] puogoas 1984s soueyeg |
epuno} eq qunoode siLp [IuA 196pe7 fesouaD Oy) JO UONDES YOY UL LLL
uoyezeidsoqul pue seHpeyjesouey = pp.
SNILNNODSV LSOD
{seqnuiw >) ‘Sue €z) -NOLLSSND
‘OSN
S10Z soquieides 191 LOULOD z (11 epeip) Buguncsoy
° i (“ ot Soper pa) 7
seAQ Wy asesid,
“seBed 9 jo sysisuoo wnpueioweu sIy) “aN
panesey 1y6uAdos|
ALVOSILYSAD YOINSS
TWNOILYN
uonjeonpy olseg
L
uogeonp® jo Jusuedag jeyen-ninzemy ¢
09) ‘ool
ot 4 surashg AloUeAu| €
te zs Suge6png z
wh ee Suyunosoy Is0D, L
‘SoyNUI SEN aidoy uoysenD
snou Ls SUNIL
GOL: SyEvW
: LS NOWWOD :
: $102 NaEINUadSS :
: WWNOGNVYOINSIA ONDSVIN :
Volusv HLNOS dO 9I8Nday
Downloaded from hlayiso.com
New
ca
JBAQ WIN] aseaig penissex iHBLAdoD
5
6 | | aosees Betz 28 ise e8
7029 SE : 000 86 SLOZ FeqUienON
70¢9 93 7280 8b” 00z $6 4 $10z 890109
A029 ¥ 7089 79 7995 Lb Oor 26 $10z Jequeydeg:
srry oez zo 006 88.y soz ysniny
SOL y 00€ £84 stoz Aine
[aie | eeene | es ess
: ainpsyag uoRIeHI09 Suo\Ied LTT
As oid you AuuOW payipaid
‘@4} MOYS 0} Apso ul poued payeHipng euy Guunp sesusdxe pue seuicoul peysedxe
y au} 12 SYOo} JuSUISTEIg euCdU psaloid Y °
7/ poued jeGpng
2u} JO uOW Yoes SuuNnp ssoueeq Ue ety yIPEud 0} JaplO UI YSeD JO SMO_INO pue
smoyjul payoipeud ye 400] 0} pasn si }eBpng YseD °
7 “y5png
yseo e pure qeUre}e}g euNooU] peysefog e UeeMmjeq eoUaJeyIp OUR UIEIGXy 1 Z
|NILaz9GNa
ZNOLLSSND
$1L0Z Jequieydag yse1 YoWWOD v (Lt pes) Suguncooy
‘ww
J8AQ WNL BSeaId penasey UBUACOD,
€ Awad e Bupyew pes
pue Uens 4e8Iq 0} papsau aem spaq JyE 1 Ajuo pue peonpoid auem spaq oS6 &
PSEA
cureidxa “sloz ysnGny 1¢ pepus seeA ey} Butinp apew
asom JeiR Spaq e[Buls oquinu ou} YM payspeEs oq spag S.qog Aillg PINCUS ZTE
g Basle b=
jpauovisi ed eudyriomeiedD
SZOVE L =
oes
00S eb2
POLI ~ ADOT
O05 ELL
“gL0z 3snGny pe pepue sesh aug Joy jujod Uane-yeosq OUR aeINIEQ ETL
juiog ueaq yeoIg CL
StOz sequisidas ye YOWUWOD € (L1 speig) Suuncsoy
Paniesay jSukdoa J8AQ WN, Bseeid penesey w6ukdoa
foot] -SwIVIN TVLOL
°
fo) $s (AO Zé6L Wg SSOUD
” JA(G06 sos) ‘sajeg Jo soQ
Sy /009 £92 (,009 €s + 000 O12) Seles
4] “stoz Ainr pe Burpue seek aun 101 word SSO1D aly JO UOREINIIEQ —¢’e
—_
= Z woos sos seqes $0 S09,
= A(00v 21) 2PaIs BuIsoID
ro} ooe ag 6E | | aozs 2 fAs00 #L (SEZ bE (WIUOW Su} 40s OG TON
q AOL 2 (009 + “00S 9) Saseyoing uo aBeweD {000 2) (009 +) (09 1) (ueo7 uo) ssuedx yses0}U}
ie Eo (soe si lasee eb Wold SujeredQ
ioe oss SeSEYOINe
ze} a Buus Pvor OL /00z OL 7000 Ot sesuedxg Aupung
10] US
7009 OF Pars BuwedO 7098 ‘7088 & 7050 # uopeieidsq
oO “sales JO }SOD Jo uoRRINDIeD 7 E 7029 7 ASbry ASSL siged peg
xe} 7008 8% 7009 1Z 7009 1% saBeyy pue Soules
(4°) eb 00s Z oosz 00s z Suysnieapy
{e) falbzt og) (ges Zr) fa(ste zy) sesuedxy Bugeiedo
cx 000 29s | a 000 29s i002 6s wooz > (A002 Ss swiodu] Bugeiedg sso1g)
a i Puunosy | 008 $ 008 $ 008 ¢ @woou) wey
oososs © |” Gupey | 7000 82 a a a
i t T 0p L OOF L OOF Lt ‘BWOOU UOISSIWWOD,
soOel | PO | pSBumeig i 7000 6E
fe) 7 - i L ii foo 2 ooz 2 ooz 9 @woouy BuReIedg JELO
1 AlORUOD | inp yA i
oO 700k 1fYO | Soupaun | © | siaz | d00 097 loos zs 000 ts woos 6 Wid SSO
wo saseyoung AMoog ze) _| -(o00 se) Aloos ze) Saleg 40 809
000 ort 000 get 000 zeL sees
SWSLSAS ANOLNSANI JOqUISAON 3240390, ydeg
. (seynutin $1 ‘sy1eW $2) € NOLLSEND quewaze}g auosyy payelorg 7TZ
OSN OSN
$10z requiaides jsey uoWWoD 9 (4) @peag) Bugunesoy SL0z Jequierdeg Ise) uOWUIOg s {14 ape) Gununosoy
Downloaded from hlayiso.com
Study this subject
Recommended for this subject
Question paper and memo
Accounting Grade 11 KwaZulu Natal June 2015 Paper & Memo
Question paper and memo
Accounting Grade 11 NSC Prelim 2015 Paper & Memo
Question paper and memo
Accounting Grade 11 September Test 2016 Paper & Memo
Memorandum
Accounting Grade 11 Eastern Cape November 2015 Memo (Eng)
Question paper
Accounting Grade 11 Eastern Cape November 2015 QP (Afr)
Memorandum
Accounting Grade 11 Gauteng November 2015 Memo
More from Grade 11 Accounting
Study guide
GR11 Accounting Practice exam November Paper 1
Question paper
Accounting Grade 11 P2 November Mock 2026 QP (Eng)
Addendum
Accounting Grade 11 P1 Eastern Cape November 2025 Addendum
Memorandum
Accounting Grade 11 P2 Eastern Cape November 2025 Memo (Eng)
Memorandum
Accounting Grade 11 P2 Eastern Cape November 2025 Memo (Afr)
Question paper