
Downloaded from hlayiso.com
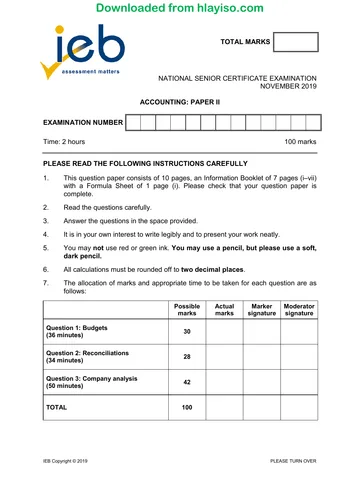
NATIONAL SENIOR CERTIFICATE EXAMINATION
NOVEMBER 2019
ACCOUNTING: PAPER II
Time: 2 hours 100 marks
INFORMATION BOOKLET
IEB Copyright © 2019 PLEASE TURN OVER
Skip to contentInformation sheet 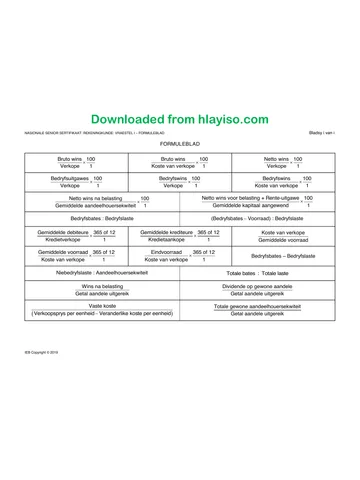
View all
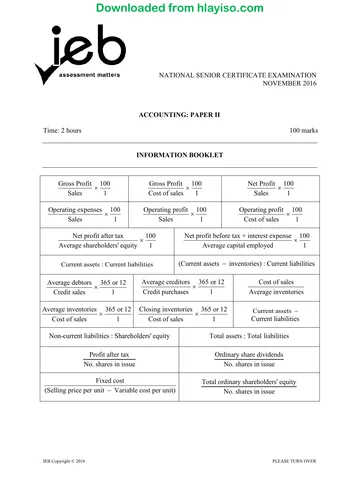
Accounting Grade 12 IEB Paper 2 2019 Information Sheet
IEB Grade 12 Accounting Paper 2 information sheet from the 2019, 7 pages. Read online or get the free PDF download.
Publisher: IEB
Accounting · Grade 12 · 2019. Information sheet, 7 pages. Read online or download the PDF.
- Subject
- Accounting
- Grade
- Grade 12
- Document type
- Information sheet
- Year
- 2019
- Paper
- 2
- Publisher
- IEB
- Curriculum
- IEB
- Pages
- 7
- File size
- 291.6 KB
Loading document…
Loading document…
1 of 7
Document textSearch extracted text and jump to a page.
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER II – INFORMATION BOOKLET Page ii of vii
QUESTION 1 BUDGETS (30 Marks; 36 Minutes)
Thabo was retrenched from his job. He is good at woodworking and would like to start a
business manufacturing kitchen cupboards instead of looking for another job. He will call it
High-Class Cupboard Designs (HCC Designs for short).
The challenge is that the bank will not loan him start-up capital or grant him an overdraft
facility in the first three months until he has proven that his business will work.
His plan is to hire and train 4 workers. He predicts that they will be able to manufacture
15 sets of cupboards in the first month, then as many as 20 sets per month as they
become more efficient and skilled. He will build up stock in March and start selling them in
April.
Thabo plans to sell each set of kitchen cupboards at a selling price of R42 000. He plans
to use a 25% mark-up on cost. He hopes to supply the following potential customers:
• He has a potential contract supplying 10 sets of kitchen cupboards per month to
Kitchen Wizard (Pty) Ltd. Kitchen Wizard will pay in the second month after delivery.
• Do It Yourself Empire has told him that they will stock 4 sets from 1 April 2020. When
all 4 sets have been sold they will pay him and buy 4 more. Thabo is hopeful that they
will sell all 4 sets in a month, so he budgeted on receiving the money in the month after
supplying them.
• Thabo is hopeful that he will be able to sell a further 6 sets of kitchen cupboards per
month to various other shops and has budgeted his sales accordingly as cash sales
from 1 April 2020.
Thabo hopes to launch his business on 1 March 2020, and he hopes to start trading on
1 April 2020, so he drew up the following cash budget:
IEB Copyright © 2019
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER II – INFORMATION BOOKLET Page iii of vii
Cash budget of HCC Designs for the two months ending April 2020
March April
RECEIPTS 400 000 ??
Cash sales 0 A
Cash from debtors 0 0
Capital 400 000 0
PAYMENTS ?? ??
Raw materials 450 000 600 000
Direct wages 24 000 24 000
Wood working equipment 220 000 0
Truck B 0
Rent of factory C 35 000
Total insurance 10 275 D
Vehicle expenses E 2 660
Office stationery F 700
Office telephone ?? ??
Factory municipal costs 6 800 G
Surplus / deficit (804 920) (431 441)
Accumulated surplus / deficit (804 920) (1 236 361)
Additional information
• The wood working equipment is depreciated at 15% p.a.
• Since Thabo cannot get a loan he has planned to buy the truck with cash to deliver the
sets of cupboards to his customers. The depreciation on the truck is calculated at 8%
per annum. The depreciation on the truck for April was R2 800.
• HCC Designs had to pay double rent in March: Rent for the month plus the deposit.
• Thabo started the insurance policy late, so he only paid for ¾ of March. From April he
will pay the full amount. The insurance is split in a ratio between the factory and the
office. The office insurance for April is R2 740.
• Thabo is expecting the vehicle expenses to increase by 40% from 1 April onwards.
• Part of the office stationery costs in March are business cards that cost R800. There
should be enough cards to last until the end of July. Thabo estimates that the rest of
the stationery costs will be similar every month.
• The factory municipal costs are going to go up by 2% in April due to an increase in
electricity tariffs.
IEB Copyright © 2019 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER II – INFORMATION BOOKLET Page iv of vii
QUESTION 2 RECONCILIATIONS (28 Marks; 34 Minutes)
PeaceOfPocket (POP) is an insurance company that insures cars. They employ
20 consultants in their call centre to help their clients record and sort out claims, and one
person, Udesh, in the finance office.
The telephone consultants refer the clients to the appropriate panel beater or garage,
depending on what is wrong with the client’s car. POP then waits for the panel beater or
garage to send them an invoice once the job is finished, which they then record in their
creditors journal.
POP’s financial year-end is 31 December.
PART A
The following statement was received from one of the panel beaters.
Bumpless (pty) ltd
76 Kruger Lane Statement no: 98
Lyttelton Hights
0357 Date: 30 November 2019
Date Transactions Debit Credit Balance
2019
Aug 5 Invoice P77 34 000 34 000
7 Invoice P79 45 750 79 750
Sept 18 Invoice P83 39 780 119 530
20 Credit note P02 3 870 115 660
30 EFT 32 300 83 360
Discount 1 700 81 660
Oct 6 Invoice P87 28 660 110 320
31 EFT 34 200 76 120
Nov 15 Invoice P90 35 900 112 020
30 Interest 462 112 482
Terms: • 5% discount granted if paid within 30 days of statement date.
• ? % per month interest charged on 90 days overdue.
Age 90 Days 60 Days 30 Days Current
analysis: ?? ?? ?? ??
IEB Copyright © 2019
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER II – INFORMATION BOOKLET Page v of vii
When comparing the statement received from Bumpless (PTY) Ltd, to the creditors
ledger, the following differences were found:
• POP has no copy of invoice P79 and when questioned, Bumpless could not find a
copy of it. POP insisted that it is an error and must be cancelled. Bumpless agreed.
• Bumpless made a mistake when recording credit note P02. The correct amount was
R3 780.
• Since invoice P79 is a mistake, Bumpless has omitted to record the discount on the
EFT dated 31 October.
• Due to the erroneous invoice P79, no interest should have been charged. This needs
to be cancelled.
• Invoice P90 was recorded in the Creditors journal as R39 500. This is an error.
• On 30 November POP made a payment via EFT to pay invoice P87 less the 5%
discount they should receive.
PART B
Bank reconciliation statement on 31 October 2019
Balance according to the bank statement ?
Outstanding deposits 11 420
Outstanding cheques: No. 99 (17 May 2019) 3 160
No. 115 (25 July 2019) 1 130
No. 127 (28 October 2019) 2 665
No. 128 (5 January 2020) 2 408
Debit balance according to the bank account 992
Other information relating to the bank account on 30 November 2019
The following cheques appeared on the bank statement on 30 November 2019:
• No. 115
• No. 127
Transactions to be used to fill in Question 2.8.
(a) Show how cheque no. 99 will be dealt with on 30 November.
(b) Show how cheque no. 128 will be dealt with on 30 November.
(c) A cheque for R3 700, dated 1 December 2019, was received from A. Brown to pay
for the excess on replacing his car door.
(d) The bank statement showed an unpaid cheque from a client for R2 160. This was
in settlement of a debt of R2 400.
IEB Copyright © 2019 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER II – INFORMATION BOOKLET Page vi of vii
QUESTION 3 COMPANY ANALYSIS (42 Marks; 50 Minutes)
Tiger Brands, a Top 40 JSE company, is one of the largest
manufacturers and marketers of fast moving consumer products
and South Africa’s largest food company.
Adapted from the Condensed consolidated income statement
for the year ended 30 September
Notes 2018 2017
Rm Rm
Revenue 28 473,9 31 297,9
Cost of sales (19 229,5) (20 856,4)
Gross profit 9 244,4 10 441,5
Operating expenses (5 923,7) (5 807,2)
Sales and distribution expenses 3 675,8 3 596,4
Marketing expenses 844,7 771,4
Other 1 403,2 1 439,4
Operating income before abnormal items 1 3 320,7 4 634,3
Costs associated with VAMP product recall (422,1) –
Other (343,5) (693,6)
Operating income after abnormal items 2 555,1 3 940,7
Finance costs (31,7) (206,6)
Investment income 730,7 533,3
Profit before taxation 3 254,1 4 267,4
Taxation (837,0) (1 234,4)
Profit for the year 2 417,1 3 033,0
Note 1: Breakdown of operating income per department
2018 2017
Rm Rm
Operating income before abnormal items
Domestic operations 3 050,8 4 235,5
Grains 1 886,0 2 361,2
Foods 827,9 1 280,2
Value Added Meat Products (VAMP) (252,0) 104,2
Other 1 079,9 1 176
Home, Personal Care and Baby 345,9 651,1
Exports and international 269,9 398,8
Exports 289,7 272,9
International – Central Africa 159,0 147,2
International – West Africa (Deli foods) (50,5) (34,5)
Deciduous Fruit (128,3) 13,2
Total operating income 3 320,7 4 634,3
Extracts from the financial report
• The suspension of operations of Value Added Meat Products (VAMP) at two
Enterprise factories due to the Listeria outbreak, had a material impact on the results.
• Despite the closures, Tiger Brands has maintained its 1 600 permanent employees.
The Enterprise factory facilities were used for training the employees and they started
manufacturing again in November 2018.
IEB Copyright © 2019
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER II – INFORMATION BOOKLET Page vii of vii
Adapted from the Condensed consolidated statement of financial position on
30 September
2018 2017 Listeria update:
ASSETS Rm Rm
Tiger Brands set
Non-current assets 13 165,4 13 237,5
aside R10 million to
Current assets 10 763,0 10 377,0 launch the country’s
Inventories 5 064,0 4 812,0 first Centre of Food
Trade and other receivables 4 117,9 4 631,6 Safety in
Cash and cash equivalents 1 581,1 933,4 collaboration with
Assets classified as held for sale – 364,7 Stellenbosch
Total assets 23 928,4 23 979,2 University.
EQUITY AND LIABILITIES
Total equity 17 465,2 A The Centre will
Non-current liabilities 1 062,2 C conduct research,
and help government
Current liabilities 5 401,0 B
ensure that food
Trade and other payables 3 841,0 ? safety regulations
Other 1 560,0 1 497,9 are based on sound
Total equity and liabilities 23 928,4 23 979,2 scientific evidence.
Glossary
• Listeria: a type of bacterium which infects humans and causes food poisoning.
Ratios for the year ended 30 September
2018 2017
Number of issued shares 189 820 000 189 820 000
Net asset value 9 201 cents 9 000 cents
Market price on 30 Sept 26 560 cents 37 735 cents
Earnings per share 1 273 cents 1 597 cents
Dividends per share 1 080 cents 1 080 cents
Return on capital employed 13,12% 17,4%
Interest rate on the loan 9,5% p.a.
Current ratio 2:1 1,8 : 1
Acid test ratio ? 1,05 : 1
Debtors collection period 53 days 54 days
Stock turnover rate 3,8 times 4,3 times
IEB Copyright © 2019
Study this subject
Revise the topics in this paper, then practise them question by question.
- Grade 12 Accounting notes
CAPS revision notes with worked examples.
- Accounting questions by topic
Past exam questions sorted by CAPS topic, with memos where available.
- Grade 12 Accounting quizzes
Short topic quizzes with instant feedback.
- All Grade 12 Accounting past papers
Past papers by year, with memos where available.
- Grade 12 IEB past papers
More Accounting and other subjects in this collection.
Recommended for this subject
More papers and memos for this grade and subject.
Information sheetIEB
Accounting Grade 12 IEB 2019 Information Sheet (Afrikaans)
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2019 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB P1 2019 Information Sheet (Afrikaans)
Information sheetIEB
Accounting Grade 12 IEB P2 2019 Information Sheet (Afrikaans)
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2018 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2018 Information Sheet
Related documents
Question paperIEB
Accounting Grade 12 IEB Paper 2 2019 Question Paper
Question paperIEB
Accounting Grade 12 IEB Paper 2 2019 Question Paper (Afrikaans)
Information sheetIEB
Accounting Grade 12 IEB Paper 2 2018 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB Paper 2 2017 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB Paper 2 2016 Information Sheet
Question paperIEB
Accounting Grade 12 IEB Paper 1 2019 Question Paper
More from Grade 12 Accounting
Question paperIEB
Accounting Grade 12 IEB Paper 1 2019 Question Paper (Afrikaans)
Question paperIEB
Accounting Grade 12 IEB Paper 1 2018 Question Paper
MemorandumIEB
Accounting Grade 12 IEB Paper 1 2018 Memo
Question paperIEB
Accounting Grade 12 IEB Paper 2 2018 Question Paper
MemorandumIEB
Accounting Grade 12 IEB Paper 2 2018 Memo
Question paperIEB