
Downloaded from hlayiso.com
TOTAL MARKS
NATIONAL SENIOR CERTIFICATE EXAMINATION
NOVEMBER 2019
ACCOUNTING: PAPER I
EXAMINATION NUMBER
Time: 2 hours 200 marks
PLEASE READ THE FOLLOWING INSTRUCTIONS CAREFULLY
1. This question paper consists of 10 pages, an Information Booklet of 8 pages (i–viii)
and a Formula Sheet of 1 page (i). Please check that your question paper is
complete.
2. Read the questions carefully.
3. Answer the questions in the space provided.
4. It is in your own interest to write legibly and to present your work neatly.
5. You may not use red or green ink. You may use a pencil, but please use a soft,
dark pencil.
6. All calculations should be rounded off to two decimal places.
7. The allocation of marks and appropriate time to be taken for each question are as
follows:
Possible Actual Marker Moderator
marks marks signature signature
Question 1: Inventory Control
35
(21 minutes)
Question 2: Financial Statements
67
(40 minutes)
Question 3: Cash Flow Statement
46
(28 minutes)
Question 4: Manufacturing and VAT
52
(31 minutes)
TOTAL 200
IEB Copyright © 2019 PLEASE TURN OVER
Skip to contentQuestion paper 
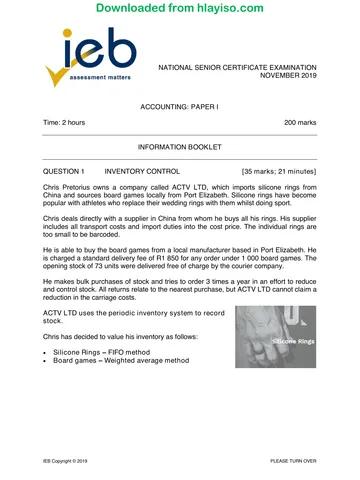
View all
Accounting Grade 12 IEB Paper 1 2019 Question Paper
IEB Grade 12 Accounting Paper 1 question paper from the 2019, 10 pages. Read online or get the free PDF download, memo linked when available.
Publisher: IEB
Accounting · Grade 12 · 2019. Question paper, 10 pages. Read online or download the PDF.
- Subject
- Accounting
- Grade
- Grade 12
- Document type
- Question paper
- Year
- 2019
- Paper
- 1
- Publisher
- IEB
- Curriculum
- IEB
- Pages
- 10
- File size
- 332.2 KB
Loading document…
Loading document…
1 of 10
Document textSearch extracted text and jump to a page.
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I Page 2 of 10
QUESTION 1 INVENTORY CONTROL [35 marks; 21 minutes]
Refer to the Information Booklet for information relating to ACTV LTD.
1.1 Calculate the rand value of the closing stock of silicone rings for the year ended
28 February 2019.
Closing stock of silicone rings (rands)
(6)
1.2 Calculate the number of units in closing stock for board games.
Closing stock of board games (units)
(4)
1.3 Calculate the cost of sales of the board games for the financial year.
Opening stock
Cost of board games available to sell
Less closing stock
Cost of sales
(12)
IEB Copyright © 2019
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I Page 3 of 10
1.4 ACTV LTD aims to achieve a mark-up of 270% but only achieved an actual mark-
up of 267%. Give two reasons why their mark-up was not achieved.
(2)
1.5 Chris is concerned that stock has been stolen from him and spends the last
weekend of the financial year counting his stock. He finds no board games have been
stolen, but counts only 6 005 rings. Calculate how many rings have been stolen.
(2)
1.6 Both stock items are kept in the same room. Why do you think so many rings were
stolen? Give one internal control measure which could be implemented to reduce
the theft of rings. This measure should support your reason.
(3)
1.7 Due to the theft of stock, Chris is considering changing over to the perpetual
inventory system. Would you support his decision? Give one reason to support
your answer.
(3)
1.8 Chris sells the majority of his rings through a retailer for R49 per ring. He has
subsequently seen his rings selling for R147 in the shops. He owns a website and
is considering selling older rings which had been returned to him, directly from this
website. He plans to sell rings for R100 each. Is this a good idea? Discuss the
ethical implications this may have between Chris, the retailer and customers.
(3)
35
IEB Copyright © 2019 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I Page 4 of 10
QUESTION 2 FINANCIAL STATEMENTS [67 marks; 40 minutes]
Refer to the Information Booklet for information relating to BARR SURF LTD.
All workings need to be shown as part marks will be allocated to them. The number
of lines does not represent the number of entries required.
2.1 Complete the Statement of Comprehensive Income (Income Statement) for the year
ending 28 February 2019.
BARR SURF LTD
Statement of Comprehensive Income for the year ending 28 February 2019
Net sales
Other operating incomes DO NOT CALCULATE
Rent Income (2 550
Fee income (108 200
Gross operating income DO NOT CALCULATE
Operating expenses (123 262)
Salaries (58 000
UIF contributions (580
Audit fees (4 200
Insurance (15 000
Sundry expenses
Operating profit before interest DO NOT CALCULATE
Interest income 0
Profit before interest expense DO NOT CALCULATE
Interest expense (20 000
Profit before taxation DO NOT CALCULATE
Net profit after taxation 108 000
(30)
IEB Copyright © 2019
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I Page 5 of 10
Calculations must be done in the boxes below.
Interest expense Insurance
Trading stock deficit/surplus Fee income
2.2 Complete the following notes to the financial statements as it would have appeared
on 28 February 2019. All workings must be shown to be awarded part marks.
ORDINARY SHARE CAPITAL AMOUNT
AUTHORISED: 1 000 000 ordinary shares
ISSUED:
625 000 Ordinary shares in issue at the start of year 2 000 000
_________ ordinary shares repurchased at _________ per
share
_________ ordinary shares at _________ in issue at the
end of the year
(6)
RETAINED INCOME AMOUNT
Retained income at the start of the year
Net profit/loss after tax for the year
Repurchase of _________shares at _______
Retained income at the end of the year
(11)
IEB Copyright © 2019 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I Page 6 of 10
TRADE AND OTHER PAYABLES AMOUNT
Trade creditors (53 000
UIF (1 160
SARS – PAYE (10 600
DO NOT
CALCULATE
(16)
2.3 What financial indicators do the directors need to consider before buying shares
back?
(2)
2.4 Inflation in South Africa is targeted between 3 and 6%. Yet insurance premiums for
BARR SURF LTD have risen by 170%. Why do you think this is the case?
(2)
67
IEB Copyright © 2019
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I Page 7 of 10
QUESTION 3 CASH FLOW STATEMENT [46 marks; 28 minutes]
Refer to the Information Booklet for information relating to Bradley Bros Ltd.
3.1 Complete the reconciliation note between profit before taxation and cash generated
from operations for the year ended 30 June 2019.
1. Reconciliation between profit before taxation and
cash generated from operations
Profit before tax
Adjustments in respect of:
Depreciation
Interest expense
Operating profit before changes in working capital
Changes in working capital:
Cash generated from operations
(13)
Calculations must be done in the boxes below.
Profit before tax Calculate trade and other payables
Depreciation Inventory
(14)
IEB Copyright © 2019 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I Page 8 of 10
3.2 Calculate the following amounts.
3.2.1 Tax paid
Workings
Amount paid:
(4)
3.2.2 Interest paid
Workings
Amount paid:
(4)
3.3 Calculate the cost price of the new vehicle bought on 1 July 2019.
Book value at beginning
Book value at end 167 500
(7)
3.4 Complete the Cash Flows fom Investing Activities section of the Cash Flow
Statement for the year ended 30 June 2019.
CASH FLOWS FROM INVESTING ACTIVITIES
Purchase of non-current assets
Proceeds from disposal of non-current assets
(4)
46
IEB Copyright © 2019
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I Page 9 of 10
QUESTION 4 MANUFACTURING AND VAT [52 marks; 31 minutes]
PART A
4.1 Complete the raw materials note as it would have appeared on 28 February 2019:
Do not calculate
(11)
4.2 Complete the direct labour note as it would have appeared on 28 February 2019:
Do not calculate
(8)
4.3 Calculate the cleaner's weekly wage if she works 48 weeks of the year.
(5)
4.4 Complete the selling and distribution note as it would have appeared on
28 February 2019 and then calculate the net profit made by Couch Worx Ltd.
Selling and distribution costs
Calculation of net profit
(16)
IEB Copyright © 2019 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I Page 10 of 10
4.5 The directors of Couch Worx Ltd are concerned about their break-even analysis as
well as their profitability. Explain using two reasons and supporting figures whether
their concerns are valid.
(4)
PART B VAT is calculated at 15%.
4.6 Show how the VAT control account will be affected by the transactions relating to
Dusi Boets Ltd. You are required to only fill in amounts under either the debit or
credit columns. Calculate how much is owed to/owed by SARS and show your
selection by circling the correct block.
VAT CONTROL
Debit Credit
Amount Owed to SARS Owed by SARS
(8)
52
Total: 200 marks
IEB Copyright © 2019
Study this subject
Revise the topics in this paper, then practise them question by question.
- Grade 12 Accounting notes
CAPS revision notes with worked examples.
- Accounting questions by topic
Past exam questions sorted by CAPS topic, with memos where available.
- Grade 12 Accounting quizzes
Short topic quizzes with instant feedback.
- All Grade 12 Accounting past papers
Past papers by year, with memos where available.
- Grade 12 IEB past papers
More Accounting and other subjects in this collection.
Recommended for this subject
More papers and memos for this grade and subject.
Question paperIEB
Accounting Grade 12 IEB Paper 1 2019 Question Paper (Afrikaans)
Question paperIEB
Accounting Grade 12 IEB Paper 2 2019 Question Paper
Question paperIEB
Accounting Grade 12 IEB Paper 2 2019 Question Paper (Afrikaans)
Question paperIEB
Accounting Grade 12 IEB Paper 1 2018 Question Paper
Question paperIEB
Accounting Grade 12 IEB Paper 2 2018 Question Paper
Question paperIEB
Accounting Grade 12 IEB Paper 1 2017 Question Paper
Related documents
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2019 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB P1 2019 Information Sheet (Afrikaans)
Question paperIEB
Accounting Grade 12 IEB Paper 1 2016 Question Paper
Information sheetIEB
Accounting Grade 12 IEB 2019 Information Sheet (Afrikaans)
Information sheetIEB
Accounting Grade 12 IEB Paper 2 2019 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB P2 2019 Information Sheet (Afrikaans)
More from Grade 12 Accounting
MemorandumIEB
Accounting Grade 12 IEB Paper 1 2018 Memo
MemorandumIEB
Accounting Grade 12 IEB Paper 2 2018 Memo
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2018 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2018 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB Paper 2 2018 Information Sheet
MemorandumIEB