
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE EXAMINATION
NOVEMBER 2018
ACCOUNTING: PAPER I
MARKING GUIDELINES
Time: 2 hours 200 marks
These marking guidelines are prepared for use by examiners and sub-examiners,
all of whom are required to attend a standardisation meeting to ensure that the
guidelines are consistently interpreted and applied in the marking of candidates'
scripts.
The IEB will not enter into any discussions or correspondence about any marking
guidelines. It is acknowledged that there may be different views about some
matters of emphasis or detail in the guidelines. It is also recognised that,
without the benefit of attendance at a standardisation meeting, there may be
different interpretations of the application of the marking guidelines.
IEB Copyright © 2018 PLEASE TURN OVER
Skip to contentMemorandum 
View all
Accounting Grade 12 IEB Paper 1 2018 Memo
IEB Grade 12 Accounting Paper 1 memorandum from the 2018, 11 pages. Read online or get the free PDF download, question paper linked when available.
Publisher: IEB
Accounting · Grade 12 · 2018. Memorandum, 11 pages. Read online or download the PDF.
- Subject
- Accounting
- Grade
- Grade 12
- Document type
- Memorandum
- Year
- 2018
- Paper
- 1
- Publisher
- IEB
- Curriculum
- IEB
- Pages
- 11
- File size
- 212.4 KB
Loading document…
Loading document…
1 of 11
Document textSearch extracted text and jump to a page.
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – MARKING GUIDELINES Page 2 of 11
QUESTION 1 MANUFACTURING
Refer to the Information Booklet for information relating to Hammond Huts.
1.1 Complete the Tangible Asset Note as it would have appeared in the
Statement of Financial Position as at 30 June 2018. You may use the
calculation blocks below to show your workings, but write your final answer
in the Note next to the question marks (?).
Vehicle depreciation calculations
New Total
300 000 × 15% × 3/12 = 11 250 1 400 000 × 15%
= 210 000 + 11 250
= (221 250)
Machinery depreciation calculations
Depreciation of old machinery sold Depreciation of machinery not sold
(700 000 – (270 000 – (120 000 – 18 000 – 15 300)
33 300)) × 15%
= 69 495 86 700 × 4/12 × 15% = 4 335
Accumulated depreciation at end of
Total depreciation for year
year
69 495 + 4 335 = 73 830 270 000 + 73 830 – 37 635
= 306 195
Disposal of machinery
Disposal
120 000 – (18 000 + 15 300 + 4 335) = 82 365
IEB Copyright © 2018 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – MARKING GUIDELINES Page 3 of 11
Vehicles Machinery
Carrying value on 1 July 2017 ?980 000 550 000
Cost 1 400 000 ?820 000
Accumulated depreciation ?(420 000) (270 000)
MOVEMENTS
Additions ?300 000 –
Disposals (120 000 – 18 000 – 15 300 –
– (82 365)
4 335)
Depreciation (221 250) (73 830)
Carrying value on 30 June 2018 1 058 750 ?393 805
Cost 1 700 000 ?700 000
Accumulated depreciation (641 250) ?(306 195)
1.2 Complete the Direct Labour Note as it would have appeared on 30 June 2018:
90 000 × 2
180 000
Wages (7 500 × 12 × 2)
42 800 2/5
17 120
Bonus (25 680 × 5/3 × 2/5 (5/3 + 2/5 = 2/3)
Medical Aid Contributions (38 400 × 60% × 2) 46 080
UIF Contribution (180 000 × 1%) 1 800
245 000
1.3 Complete the Factory Overheads Note as it would have appeared on
30 June 2018:
Indirect materials (14 500 + 20 700 –
8 000
17 200) × 4/9
Depreciation on machinery *73 830
Insurance (4 680 × 3/12) 1 170
83 000
IEB Copyright © 2018 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – MARKING GUIDELINES Page 4 of 11
1.4 Calculate the cost of finished goods produced during the year ended
30 June 2018:
Opening stock of finished goods 54 000
Cost of finished goods produced during the year
482 000
(from PCS)
Closing stock of finished goods (32 000)
Cost of finished goods sold/cost of sales 504 000
1.5 Complete the Production Cost Statement for the year ended 30 June 2018:
Direct/Prime costs (860 × 400) 344 000
Direct materials (344 000 – 245 000) 99 000
Direct labour see 1.2 245 000
Factory overhead costs see 1.3 83 000
Total manufacturing costs 427 000
Work in progress (1 July 2017) 220 000
647 000
Work in progress (30 June 2018)
(165 000)
balancing amt. must be in brackets
Cost of production of finished goods see 1.4 482 000
IEB Copyright © 2018 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – MARKING GUIDELINES Page 5 of 11
QUESTION 2 FINANCIAL STATEMENTS
Refer to the Information Booklet for information relating to NDIV Limited.
All workings need to be shown as part marks will be allocated to them. You
may use the calculation blocks on the next page to show your workings, but your
final answer must be written in the Statement of Comprehensive Income. The
number of lines does not represent the number of entries required.
2.1 Complete the Statement of Comprehensive Income (Income Statement) for
the year ending 28 February 2018.
NDIV Limited
Statement of Comprehensive Income for the year ending
28 February 2018
Net sales (3 321 000 – 21 000) 3 300 000
Cost of sales (2 214 000 – 14 000)or 10 500 (2 200 000)
Gross profit 1 100 000
Other operating incomes DO NOT CALCULATE
• Rent income (146 944 – 12 544) 134 400
• Discount received (3 300 – 700) 2 600
• Provision for bad debts adjusted or decreased in
175
provision (4 100 – 3 925)
Gross operating income DO NOT CALCULATE
Operating expenses DO NOT CALCULATE
• Directors' fees 56 000
• Audit fees (30 000 +21 000) 51 000
• Consumable stores (14 600 – 4 500) 10 100
• Bad debts (1 500 + 6 500) 8 000
• Depreciation 19 255
Trading stock deficit 21 300
• Loss on sale of vehicle 3 479
• Stock loss (25 000 × 40%) 10 000
Operating profit before interest DO NOT CALCULATE
Interest income 0
Profit before interest expense DO NOT CALCULATE
Interest expense (30 000 + 4 375) (34 375)
Profit before taxation DO NOT CALCULATE
• Taxation for the year (302 000)
Net profit after taxation DO NOT CALCULATE
IEB Copyright © 2018 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – MARKING GUIDELINES Page 6 of 11
Calculations
Trading stock deficit Interest expense
(185 000 + 14 000 – 25 000 – 370 000 × 3/12 × 10%
152 700)= 21 300 = 9 250
335 000 × 9/12 × 10%
= 25 125
= (34 375)
Rent income Profit/loss on sale of asset
12 × 100 = 1 200
1 × 112 = 112 114 000 – 44 521 – 66 000 loss
= 1 312
112
146 944 × = 12 544
1 312
2.2 Complete the following Notes to the Financial Statements as it would have
appeared on 28 February 2018. All workings must be shown to be awarded
part marks.
TRADE AND OTHER RECEIVABLES AMOUNT
Net trade debtors DO NOT CALCULATE
Trade debtors (85 000 – 6 500)+66 000 car 78 500 or 93 500
Provision for bad debts (78 500 × 5%)
(3 925)
or 4 100 – 175
Accrued income (15 000 or debtors for
15 000
insurance)
SARS (income tax) (310 000 – 302 000 or + in
8 000
trade and other payables)
DO NOT CALCULATE
TRADE AND OTHER PAYABLES AMOUNT
Trade creditors (99 000 + 3 200) 102 200
Income received in advance(146 944 – 34 400) 12 544
Accrued expenses (21 000 + 4 375 25 375
Shareholders for dividends(125 000 × 58 c) 72 500
Short-term portion of loan 35 000
DO NOT CALCULATE
IEB Copyright © 2018 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – MARKING GUIDELINES Page 7 of 11
2.3 Both audit fees and director fees are listed as expenses in the Statement of
Comprehensive Income. What is the difference between the role of an
auditor and the role of a director?
0 1 2
Learner does not know Learner has described Learners can clearly
the role of an auditor or the role of either an describe the difference
director. auditor or a director. between an auditor and
a director.
Director: manages operations of a company. Draws up and presents
financial statements.
Auditor: checks financial statements. Reports on fair representation of
financial statements.
2.4 2.4.1 What was the interim dividend per share?
123 – 58 = 65 cents per share
2.4.2 Give one reason why you think the final dividend was so much less
than the interim dividend.
Profits were lower than expected or maybe historically they paid
58 cents and 65 cents per share for final and interim dividends.
IEB Copyright © 2018 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – MARKING GUIDELINES Page 8 of 11
QUESTION 3 CASH FLOW STATEMENT
Refer to the Information Booklet for information relating to Stubar Ltd.
3.1 Complete the Reconciliation Note between profit before taxation and cash
generated from operations for the year of the Cash Flow Statement for the
year ended 30 September 2018. You may use the calculation blocks below
the Reconciliation Note to do your workings, but your final answer must be
written in the Reconciliation Note.
1. Reconciliation between profit before taxation
and cash generated from operations
• Profit before tax (648 000 × 100/72) 900 000
Adjustments in respect of:
• Depreciation 24 008
Interest expense (4 166 – 2 000) × 12 25 992
Operating profit before changes in working capital 950 000
Changes in working capital: (16 727) adding
• Decrease in inventory (345 000 – 310 000) 35 000
• Increase in trade and other receivables (70 120)
• Increase in trade and other payables 18 393
Cash generated from operations 933 273
Calculations
Calculate trade and other Calculate trade and other
receivables payables
(117 500 + 6 280) – (45 000 + (107 000 + 4 840 + 3 333) – (91
5 520 + 3 140)= 70120 000 + 3 225 + 2 555)
= 18 393
3.2 Calculate the following amounts.
3.2.1 Dividends paid
Workings
(120 000 + 30 000) × 7c = 10 500 interim
120 000 + 30 000 – 20 000 × 12c = 15 600 final
– 6 000 – 26 100 +15 600
Amount paid: 16 500
IEB Copyright © 2018 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – MARKING GUIDELINES Page 9 of 11
3.2.2 Tax paid
Workings
[252 000
– 146 792 – (900 000 – 648 000)] – 23 584
Amount paid: 422 376
3.3 Complete the Cash Flows from Financing Activities Section of the Cash
Flow Statement for the year ended 30 September 2018.
CASH FLOWS FROM FINANCING ACTIVITIES
Repayment of loan (2 000 × 12) (24 000)
Proceeds from loan (500 000 + 24 000 – 234 000)
290 000
Proceeds from issue of shares 174 000
Repurchase of shares 20 000 × R7,50 (150 000)
IEB Copyright © 2018 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – MARKING GUIDELINES Page 10 of 11
QUESTION 4 VAT AND INVENTORY
Refer to the Information Booklet for information relating to Shick Chicken.
4.1 Calculate the rand value of the closing stock on 30 November 2018.
320 + 1 050 – 1 150 = 220 kgs
the two quantities must add up to 220
The two prices must be R85 and R82
110 × 85 = R9 350 or 112 × 85 = 9 520
110 × 82 = R9 020 or 108 × 82 = 8 856
R9 350 + R9 020 =R18 370
Or 9 520 + 8 856 = R18 430
4.2 Calculate the cost of sales for the financial year.
Opening stock 20 480
Purchases 27 360 + 31 200 +13 120 + 11 050
Or 164 drawings 81 030
– 170 drawings – 1 530 (18 × R85) returns
Less closing stock (18 370)
Cost of sales 83 140
4.3 Calculate the mark-up achieved by Shick Chicken for the financial year.
Sales: 1 150 × 99 = 113 850
Cost of Sales: 83 140
113 850 – 83 140 / 83 140 = 30 710 / 83 140 = 36,94%
4.4 Considering the type of product they buy and sell, which two stock control
measures are absolutely essential in order to avoid possible legal action
being taken against them?
• Must relate to frozen chickens
• Discuss issues related to refrigeration
• Policy of no returns on frozen chickens
• The chicken must be kept frozen both in the business and in the
transport process.
• The "sell by" date must be indicated on all stock.
• Labelling with correct ingredients or Halaal
• Have backup generator in case of power failure
• No tampering with weight
• Do sample testing on quality. Must adhere to health and safety
requirements
IEB Copyright © 2018
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – MARKING GUIDELINES Page 11 of 11
4.5 Use only Information C to calculate VAT. Then circle if this is to be paid to
SARS or received from SARS. (Some amounts might include cents.)
Calculations Check grouping
Opening sales purchases returns drawings Dis rec Bad debts
– 3 100 + 2 079 – 1 547 + 214,20 + 23,80 + 448 – 140
= – 2 022
Afrikaans scripts can have + 488 or – 488
2 022 owed by SARS depending on answer
2 918 for Afrikaans
Total: 200 marks
IEB Copyright © 2018 PLEASE TURN OVER
Study this subject
Revise the topics in this paper, then practise them question by question.
- Grade 12 Accounting notes
CAPS revision notes with worked examples.
- Accounting questions by topic
Past exam questions sorted by CAPS topic, with memos where available.
- Grade 12 Accounting quizzes
Short topic quizzes with instant feedback.
- All Grade 12 Accounting past papers
Past papers by year, with memos where available.
- Grade 12 IEB past papers
More Accounting and other subjects in this collection.
Recommended for this subject
More papers and memos for this grade and subject.
MemorandumIEB
Accounting Grade 12 IEB Paper 2 2018 Memo
MemorandumIEB
Accounting Grade 12 IEB Paper 1 2017 Memo
MemorandumIEB
Accounting Grade 12 IEB Paper 2 2017 Memo
MemorandumIEB
Accounting Grade 12 IEB Paper 1 2016 Memo
MemorandumIEB
Accounting Grade 12 IEB Paper 2 2016 Memo
Question paperIEB
Accounting Grade 12 IEB Paper 1 2019 Question Paper
Related documents
Question paperIEB
Accounting Grade 12 IEB Paper 1 2018 Question Paper
Information sheetIEB
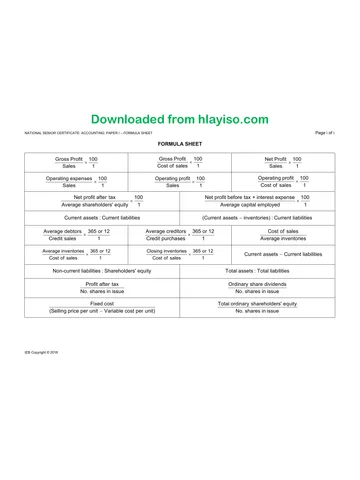
Accounting Grade 12 IEB Paper 1 2018 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2018 Information Sheet
Question paperIEB
Accounting Grade 12 IEB Paper 2 2018 Question Paper
Information sheetIEB
Accounting Grade 12 IEB Paper 2 2018 Information Sheet
Question paperIEB
Accounting Grade 12 IEB Paper 1 2019 Question Paper (Afrikaans)
More from Grade 12 Accounting
Question paperIEB
Accounting Grade 12 IEB Paper 2 2019 Question Paper
Question paperIEB
Accounting Grade 12 IEB Paper 2 2019 Question Paper (Afrikaans)
Information sheetIEB
Accounting Grade 12 IEB 2019 Information Sheet (Afrikaans)
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2019 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB P1 2019 Information Sheet (Afrikaans)
Information sheetIEB