
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE EXAMINATION
NOVEMBER 2019
ACCOUNTING: PAPER I
Time: 2 hours 200 marks
INFORMATION BOOKLET
QUESTION 1 INVENTORY CONTROL [35 marks; 21 minutes]
Chris Pretorius owns a company called ACTV LTD, which imports silicone rings from
China and sources board games locally from Port Elizabeth. Silicone rings have become
popular with athletes who replace their wedding rings with them whilst doing sport.
Chris deals directly with a supplier in China from whom he buys all his rings. His supplier
includes all transport costs and import duties into the cost price. The individual rings are
too small to be barcoded.
He is able to buy the board games from a local manufacturer based in Port Elizabeth. He
is charged a standard delivery fee of R1 850 for any order under 1 000 board games. The
opening stock of 73 units were delivered free of charge by the courier company.
He makes bulk purchases of stock and tries to order 3 times a year in an effort to reduce
and control stock. All returns relate to the nearest purchase, but ACTV LTD cannot claim a
reduction in the carriage costs.
ACTV LTD uses the periodic inventory system to record
stock.
Chris has decided to value his inventory as follows:
Silicone Rings – FIFO method
Board games – Weighted average method
IEB Copyright © 2019 PLEASE TURN OVER
Skip to contentInformation sheet 
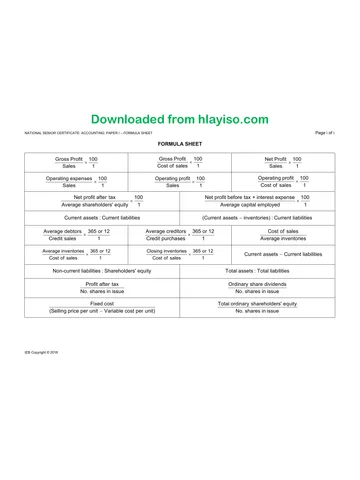
View all
Accounting Grade 12 IEB Paper 1 2019 Information Sheet
IEB Grade 12 Accounting Paper 1 information sheet from the 2019, 8 pages. Read online or get the free PDF download.
Publisher: IEB
Accounting · Grade 12 · 2019. Information sheet, 8 pages. Read online or download the PDF.
- Subject
- Accounting
- Grade
- Grade 12
- Document type
- Information sheet
- Year
- 2019
- Paper
- 1
- Publisher
- IEB
- Curriculum
- IEB
- Pages
- 8
- File size
- 387.1 KB
Loading document…
Loading document…
1 of 8
Document textSearch extracted text and jump to a page.
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – INFORMATION BOOKLET Page ii of viii
Information for the year ended 28 February 2019:
Silicone rings Board games
Per Per
Total Total value
Details Date Units unit Units unit
value (R) (R)
(R) (R)
1 Mar.
Opening stock 7 500 8,00 60 000 73 375 27 375
2018
Total purchases 11 700 100 405 685 258 000
30 Apr.
Purchases 4 200 8,00 33 600 100 382 38 200
2018
30 Sep.
2 800 8,50 23 800 85 380 32 300
2018
30 Nov.
4 700 9,15 43 005 500 375 187 500
2018
5 Oct.
Returns 120 ? ? – – –
2018
31 Dec.
Returns 185 ? ? 8 ? ?
2018
28 Feb.
Closing stock 6 110 ? ? ? ? ?
2019
Sales for the year 12 785 49 626 465 606 500 303 000
IEB Copyright © 2019
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – INFORMATION BOOKLET Page iii of viii
QUESTION 2 FINANCIAL STATEMENTS [67 marks; 40 minutes]
The information that follows refers to BARR SURF LTD.
BARR SURF LTD sells new and used surfboards and offers surf lessons for which
they charge a fee income of R450 per lesson.
BARR SURF LTD has an authorised share capital of 1 000 000 shares. 625 000
shares had been issued on 28 February 2018 at an average price of R3,20 per share.
The figures already entered into the Statement of Comprehensive Income are from the
pre-adjusted trial balance on 28 February 2019.
A. Extract from the financial statements as at 28 February 2019 before the
adjustments below.
28 February 2019 28 February 2018
Trading stock 75 000 80 000
Retained income ? 32 000
Sundry expenses Balancing figure for income statement
Loan: SB Bank @ 10,25% 223 250 235 000
SARS – Income Tax 40 000 (dr) ?
B. Adjustments and additional information that have not been taken into account.
1. BARR SURF LTD operates on a 25% mark-up policy on all sales. Last year
sales amounted to R800 000. BARR SURF LTD is pleased to announce a
10% increase in net sales in this year's financials. There were no debtors'
allowances for the year.
2. Nordic Nicky is a tourism company which brings tourists into South Africa
from Norway. They use BARR SURF LTD to run all their surf lessons. On
21 February 2019 BARR SURF LTD received a cheque from Nordic Nicky in
full payment for 2 groups who will receive lessons as follows:
Date Name of group Number of lessons
21 February 2019 Nordic warriors 15
7 March 2019 Icy surfers 4
No entries have been made in respect of these lessons.
3. Sam SurfSki Ltd has rented a storeroom from BARR SURF LTD for R850 per
month since 1 November 2018.
4. Two new surfboards with a cost price of R5 500 each were returned to the
manufacturers, Stu Surf Designs, as they were damaged in transit. A debit
note was issued.
IEB Copyright © 2019 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – INFORMATION BOOKLET Page iv of viii
5. A physical stocktaking was done, which revealed that R67 000 worth of
trading stock was on hand on 28 February 2019.
6. A new employee, E. van Vuuren, was omitted from the February 2019
salaries journal in error. Her salary details are listed below.
Basic salary 14 500
PAYE 2 610
UIF deduction 1%
BARR SURF LTD also contributes 1% to the UIF.
7. A further R1 500 is still owed to the auditors in respect of their fees.
8. Included in insurance is an annual payment for R9 468 which was taken out
on a new company vehicle bought on 1 June 2018 for R172 500 cash. This
is the only asset the company owns which will depreciate.
9. Depreciation is calculated at 20% per annum on cost price.
10. The loan statement received from KB bank on 28 February 2019 reflected
the following:
Balance on 1 March 2018 235 000
Repayments during the year including interest 35 838
Interest ?
Balance on 28 February 2019 223 250
Interest is capitalised and has not yet been recorded in full for the year.
The loan was not increased during the current financial year.
They intend to pay R11 500 of the capital amount next year.
11. The provisional tax payments for the year have been paid. Tax was
calculated at 28% on profit before taxation.
12. After considering the financial implications a buyback of shares entails, it
was decided by the directors on 1 December 2018 to repurchase 4% of the
shares currently in issue. These shares were repurchased at R4,50. No
entries have been made for this transaction.
13. Directors declared an interim dividend on 31 August 2018 of 7 cents per
share. The final dividend per share recommended by the directors on
28 February 2019 was 5 cents per share.
14. The net profit after tax was calculated to be R108 000.
IEB Copyright © 2019
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – INFORMATION BOOKLET Page v of viii
QUESTION 3 CASH FLOW STATEMENT [46 marks; 28 minutes]
Bradley Bros Ltd is a company which specialises in water polo equipment and kit. They
supply to all areas of South Africa. Their financial year ends on 30 June 2019. It has been
a tough year for the company and so directors have decided not to declare any dividends
at the end of the financial year.
INFORMATION
1. Extracts from the Financial Statements of Bradley Bros Ltd.
30 June 2019 30 June 2018
R126 000
Ordinary share capital ?
(42 000 shares)
Land and Buildings 1 850 000 1 000 000
Vehicles ? 335 000
Accumulated depreciation 13 300 163 480
Inventory ? 220 000
Trade and other receivables 1 580 2 200
Cash and cash equivalents 22 000 18 500
2. Extract from the notes to the Financial Statements of Bradley Bros Ltd.
RETAINED INCOME AMOUNT
Balance on 1 July 2018 55 000
Net profit after tax ?
Dividends paid ?
Balance on 30 June 2019 52 500
TRADE AND OTHER PAYABLES
AMOUNT
(These were the only current liabilities)
2019 2018
Trade creditors 13 500 22 000
Income received in advance 880 540
Accrued expenses (interest on loan) 1 690 1 200
Shareholders for dividends 0 8 240
SARS (income tax) 4 418 4 222
20 488 36 202
IEB Copyright © 2019 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – INFORMATION BOOKLET Page vi of viii
3. Shares and dividends:
Bradley Bros Ltd has an authorised share capital of 200 000 shares.
On 1 December 2018 Bradley Bros Ltd issued 10 000 new shares at R3,50 per
share. These new shareholders were entitled to the interim dividend paid on
31 December 2018.
No shares were repurchased during the financial year.
4. Ratios:
You will need to use these ratios to calculate the missing figures (?).
Return on shareholders equity amounted to 8% for the year ended 30 June 2019.
The current ratio was 12:1 based on the year end figures.
5. Taxation:
Income tax for the year was calculated at R5 221.
6. Non Current Assets:
The only depreciable non-current asset the business owns is a delivery van which
was bought on 1 July 2015. On 1 January 2019 Bradley Bros Ltd decided to sell
this delivery vehicle at book value (originally bought for R335 000) which had
needed constant maintenance since January 2018.
On 1 July 2018 accumulated depreciation amounted to R163 480. Depreciation is
calculated at 20% on carrying value. A new vehicle was purchased on 1 June 2019.
This vehicle's depreciation is calculated at a different rate. By 1 July 2019 it had
depreciated by R13 300.
7. Interest:
Interest on loan as per income statement amounted to R23 200. Interest is paid
separately and not capitalised to the loan account. Interest expense relates to
the loan only.
IEB Copyright © 2019
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – INFORMATION BOOKLET Page vii of viii
QUESTION 4 MANUFACTURING AND VAT [52 marks; 31 minutes]
PART A The information below refers to Couch Worx Ltd.
VAT IS CALCULATED AT 15%
Couch Worx Ltd manufactures luxury couches. Their financial year begins on 1 March
each year. Their couches are manufactured in a factory in Johannesburg which has floor
space of 840 m2. They also own two sales offices, one in Cape Town (68 m2) and the other
in Johannesburg (82 m2). The sales offices are small and manned by 1 staff member in
each office. They each earn a basic salary of R13 500 per month. There is no work in
progress at the beginning or end of the year. Finished couches are dispatched to the
sales office where they are on show for customers to buy.
INFORMATION
A. The following balances were found in the stock accounts, but the inexperienced
bookkeeper has recorded them as VAT inclusive amounts:
28 Feb 2019 28 Feb 2018
Raw materials stock (VAT inclusive) R 178 825 ?
On 1 March 2018 the VAT on raw materials stock amounted to R30 000.
55% of all purchases are paid in cash. The remainder is done on credit. Cash
purchases of raw materials amounted to R27 500 (VAT exclusive).
Couch Worx Ltd has a long-standing relationship with Rapid Rail who transports
all their raw materials and offers a 4% discount on their services. The
bookkeeper was unaware of this and has not recorded any discounts; he also
incorrectly allocated the carriage on raw materials.
B. Labour:
5 factory staff who work on the production line each receive a gross salary of
R7 200 per month.
The UIF was deducted and contributed at 1% per month.
An optional pension agreement states that Couch Worx Ltd will contribute 5% of
gross salary towards pension if the factory worker does the same. Only 3
factory staff have taken up this offer.
Contributions apply to direct wages only.
Couch Worx Ltd employs one cleaner who works 3 days in their Johannesburg
factory and 2 days in their Johannesburg sales office. The Cape Town office
does not employ a cleaner.
The cleaner's wages were incorrectly allocated to the selling and distribution
note only.
C. Additional information:
The entire rent expense has been allocated to the selling and distribution note.
However, it should have been allocated as per floor space used.
On 28 February 2019 R1 000 worth of electricity was bought for each of the
3 premises to cover the electricity bill for March 2019. 80% of the electricity bill
listed in the sales and distribution note was for the factory.
Selling price per unit amounted to R11 720.
IEB Copyright © 2019 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – INFORMATION BOOKLET Page viii of viii
D. The following appeared in the selling and distribution note of Couch Worx Ltd.:
Salaries & wages R360 000
Rent expense R627 000
Electricity R16 000
Carriage on raw materials R1 900
E. Income Statement for the period ended 28 February 2019 of Couch Worx Ltd.:
Sales R5 860 000
Cost of sales R4 688 000
Gross profit R1 172 000
Admin expense R0
Selling and distribution ?
Net profit ?
F. Break-even analysis:
28 Feb 2019 28 Feb 2018
Break-even point 140 170
Number of units sold 500 520
Units produced 525 525
PART B The information below refers to Dusi Boets Ltd and should only be
used to complete Question 4.6.
The business is a registered VAT vendor and uses the invoice basis to record VAT which is
charged at 15%. They are required to pay VAT every two months. They have not completed
their calculation of the VAT due to/owed by SARS for the month of 28 February 2019
because the bookkeeper is unsure of how to deal with the following VAT entries.
The Vat Control Account had a balance of R23 250 due to SARS on 1 February 2019.
Cash sales for the month of February totalled R469 200 (VAT inclusive).
Total credit purchases amounted to R14 950 (VAT inclusive). R6 000 worth of raw
materials (VAT exclusive) were sent back to the supplier.
A debtor, C. de Villiers, who bought goods in May 2018 for R11 720 (VAT exclusive)
has still not paid his account, it has been decided that this debt will be written off.
Discount of R115 (VAT inclusive) granted to G. Gearing (a debtor) has been cancelled
as his cheque for R815 has been rejected by the bank.
IEB Copyright © 2019
Study this subject
Revise the topics in this paper, then practise them question by question.
- Grade 12 Accounting notes
CAPS revision notes with worked examples.
- Accounting questions by topic
Past exam questions sorted by CAPS topic, with memos where available.
- Grade 12 Accounting quizzes
Short topic quizzes with instant feedback.
- All Grade 12 Accounting past papers
Past papers by year, with memos where available.
- Grade 12 IEB past papers
More Accounting and other subjects in this collection.
Recommended for this subject
More papers and memos for this grade and subject.
Information sheetIEB
Accounting Grade 12 IEB 2019 Information Sheet (Afrikaans)
Information sheetIEB
Accounting Grade 12 IEB P1 2019 Information Sheet (Afrikaans)
Information sheetIEB
Accounting Grade 12 IEB Paper 2 2019 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB P2 2019 Information Sheet (Afrikaans)
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2018 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2018 Information Sheet
Related documents
Question paperIEB
Accounting Grade 12 IEB Paper 1 2019 Question Paper
Question paperIEB
Accounting Grade 12 IEB Paper 1 2019 Question Paper (Afrikaans)
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2017 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2016 Information Sheet
Question paperIEB
Accounting Grade 12 IEB Paper 2 2019 Question Paper
Question paperIEB
Accounting Grade 12 IEB Paper 2 2019 Question Paper (Afrikaans)
More from Grade 12 Accounting
Question paperIEB
Accounting Grade 12 IEB Paper 1 2018 Question Paper
MemorandumIEB
Accounting Grade 12 IEB Paper 1 2018 Memo
Question paperIEB
Accounting Grade 12 IEB Paper 2 2018 Question Paper
MemorandumIEB
Accounting Grade 12 IEB Paper 2 2018 Memo
Information sheetIEB
Accounting Grade 12 IEB Paper 2 2018 Information Sheet
Question paperIEB