
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE EXAMINATION
NOVEMBER 2016
ACCOUNTING: PAPER I
Time: 2 hours 200 marks
INFORMATION BOOKLET
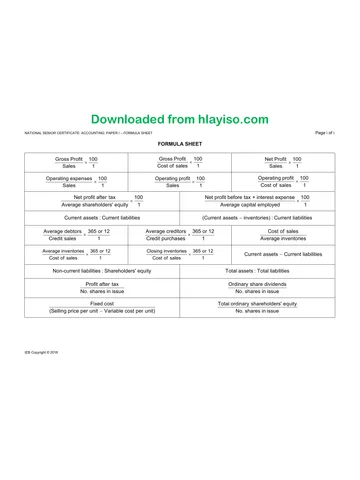
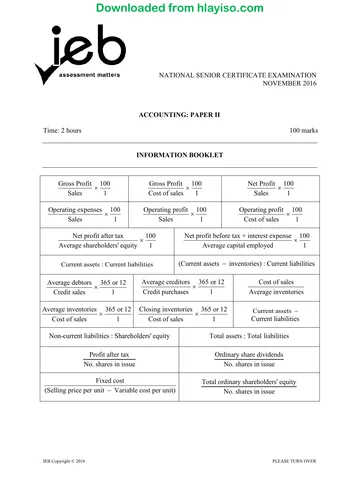
Gross Profit 100 Gross Profit 100 Net Profit 100
× × ×
Sales 1 Cost of sales 1 Sales 1
Operating expenses 100 Operating profit 100 Operating profit 100
× × ×
Sales 1 Sales 1 Cost of sales 1
Net profit after tax 100 Net profit before tax + interest expense 100
× ×
Average shareholders' equity 1 Average capital employed 1
Current assets : Current liabilities (Current assets − inventories) : Current liabilities
Average debtors 365 or 12 Average creditors 365 or 12 Cost of sales
× ×
Credit sales 1 Credit purchases 1 Average inventories
Average inventories 365 or 12 Closing inventories 365 or 12
× × Current assets − Current liabilities
Cost of sales 1 Cost of sales 1
Non-current liabilities : Shareholders' equity Total assets : Total liabilities
Profit after tax Ordinary share dividends
No. shares in issue No. shares in issue
Fixed cost Total ordinary shareholders' equity
(Selling price per unit − Variable cost per unit) No. shares in issue
IEB Copyright © 2016 PLEASE TURN OVER
Skip to contentInformation sheet 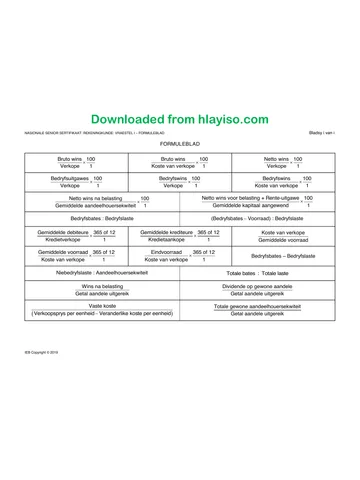
View all
Accounting Grade 12 IEB Paper 1 2016 Information Sheet
IEB Grade 12 Accounting Paper 1 information sheet from the 2016, 9 pages. Read online or get the free PDF download.
Publisher: IEB
Accounting · Grade 12 · 2016. Information sheet, 9 pages. Read online or download the PDF.
- Subject
- Accounting
- Grade
- Grade 12
- Document type
- Information sheet
- Year
- 2016
- Paper
- 1
- Publisher
- IEB
- Curriculum
- IEB
- Pages
- 9
- File size
- 260.3 KB
Loading document…
Loading document…
1 of 9
Document textSearch extracted text and jump to a page.
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – INFORMATION BOOKLET Page ii of ix
QUESTION 1 INVENTORY SYSTEMS (32 marks, 19 minutes)
Information relating to Weighcomm Scales
Weighcomm Scales supplies seafood retailers with specialised electronic scales. They use the
periodic inventory system to record their stock, and the FIFO method to value it. The financial year
ends on 31 July 2016.
1. Below is the stock record of electronic scales purchases for the year. Prices exclude VAT.
Number of
units Unit cost Total cost
Opening stock (1 August 2015) 200 R2 100 R420 000
Purchases during the year 1 350 R2 942 000
November 2015 320 R2 180 R697 600
February 2016 540 R2 160 R1 166 400
July 2016 490 R2 200 R1 078 000
2. Gross sales for the year were R4 375 320 including VAT.
3. Debtors' returns amounted to R19 000 excluding VAT (5 units). These were all returns of
stock.
4. The following credit note for scales returned to a supplier was found in the clerk's desk
drawer. It has not been processed and related to stock bought in July 2016. There were no
other credit notes during the year.
Weighcomm Scales Ltd
17 Beviss Crescent
New Germany
Tel: (031) 703 2555 Fax: (031) 703 2566 e-mail: enquires@weighcommscales.co.za
<www.weighcommscales.com>
CREDIT NOTE: 5664/07 DATE: 31 JULY 2016
Address to: CROSSFIT SCALES
210 NORTH COAST ROAD
DURBAN
QUANTITY ITEM UNIT COST (Excl. VAT) TOTAL
12 Electronic scale ? ?
VAT ?
5. According to the physical stock count on 31 July 2016, the business had 510 units on hand.
IEB Copyright © 2016
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – INFORMATION BOOKLET Page iii of ix
QUESTION 2 COMPANY FINANCIAL STATEMENTS (70 marks, 42 minutes)
Information relating to Impumelelo Limited
Impumelelo Limited
Pre-adjustment Trial Balance for the year ended 31 October 2016
R R
Balance Sheet Section
Ordinary share capital ?
Retained income ?
Land and buildings 4 064 000
Vehicles 1 850 000
Accumulated depreciation on vehicles 1 729 000
Fixed deposit: Rand Merchant at 10,5% p.a. 135 000
Trading stock 360 870
Debtors control 161 969
Bank 32 740
Loan: Capitec Bank 300 000
Creditors for salaries 25 100
SARS: PAYE 12 050
Unemployment insurance fund (UIF) 979
Creditors control 229 120
Provision for bad debts 7 930
SARS: Income tax 289 000
Nominal Accounts Section
Sales 2 435 000
Cost of sales 1 521 875
Debtors' allowances 3 725
Rent income 144 313
Audit fees 25 000
Directors fees 159 600
Sundry expenses 116 649
Bad debts 11 594
Salaries 240 000
Interest on fixed deposit 9 050
Loss on disposal of asset 6 000
Ordinary share dividends 140 000
9 085 282 9 085 282
IEB Copyright © 2016 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – INFORMATION BOOKLET Page iv of ix
Additional information and adjustments that still need to be taken into account:
1. The following adjustments relate to their debtors:
1.1 A credit note dated 31 October 2016 was issued for defective stock with a selling
price of R2 256. The company consistently applies a mark-up of 60% on cost. These
goods were returned to the supplier.
1.2 Provision for bad debts needs to be adjusted to R8 200.
2. Rental income for November 2016 was received and recorded on 25 October 2016. The
premises were occupied for the entire year.
3. Impumelelo Limited paid a 40% deposit on their audit fees for the year. The balance will be
settled on 7 November 2016.
4. According to the physical stock count, trading stock on hand amounted to R358 240.
5. The creditors for salaries figure of R25 100 in the pre-adjustment trial balance reflected the
following 2 situations:
5.1 The salaries clerk had incorrectly processed the October salary of employee Jack
Jones who had left the company on 30 September 2016.
The details of his October salary are as follows:
GROSS
R28 000 DEDUCTIONS: CONTRIBUTIONS
SALARY
PAYE: R7 852
UIF: R148 UIF: R148
(Ignore the maximum for (Ignore the maximum for
UIF) UIF)
Contributions are debited to the salaries account.
5.2 The remaining salary was for an employee who requested that his October salary
only be paid on 1 November 2016.
5.3 Payments to SARS and the various funds will only be made on 1 November 2016.
6. The fixed deposit was increased by R25 000 on 1 July 2016. This has been recorded.
Interest is not capitalised. Outstanding interest needs to be accounted for.
7. Only one asset, a vehicle, was sold at the beginning of the year. The book value of this
vehicle on the date of sale was R20 000. It was sold for R24 000 cash. All the transactions
relating to the transfer of the cost price and accumulated depreciation of the asset were
correctly transferred to the asset disposal account, but the bookkeeper recorded the receipt
of cash in the CRJ and the asset disposal account as R14 000 instead of R24 000.
8. The remaining vehicles must be depreciated to a book value of R15 000.
IEB Copyright © 2016
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – INFORMATION BOOKLET Page v of ix
9. Impumelelo Limited took out a loan from Capitec Bank on 1 November 2015 on the
agreement that they would pay back a fixed amount of the loan each year as well as any
interest expense for that year. The following table shows the transactions related to the loan
for the financial year ending 31 October 2016:
Opening balance at 1 November 2015 R420 000
Add: Interest capitalised ?
Less: Repayments and interest payments made during the year (166 200)
Closing balance at 31 October 2016 300 000
Impumelelo Limited has budgeted to repay the same capital portion of the loan next year.
10. The following share transactions took place during the year:
• On 31 October 2015 the company had shares in issue with a weighted average of R6,90
per share
• On 1 November 2015 the company issued a further 125 000 ordinary shares at R7,30
per share. This transaction has been recorded.
• On 30 September 2016 the company repurchased 37 500 shares at R8,50 per share from
the estate of a deceased shareholder
• On 31 October 2016 director A. Shaw was issued 2 500 ordinary shares at R7,40 each in
lieu of his outstanding directors fees. No entry has been made to record this.
11. On completion of the audit for the year it was calculated that Impumelelo Limited owed
SARS a further R11 450 for Income Tax.
12. On 31 October 2016, the directors declared a final dividend of 80 cents per share. The
shares issued to director A. Shaw DO NOT qualify for this dividend.
IEB Copyright © 2016 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – INFORMATION BOOKLET Page vi of ix
QUESTION 3 CASH FLOW STATEMENTS (50 marks, 30 minutes)
Information relating to Claxton LTD.
1. Extract from the Statement of Comprehensive Income (Income Statement) for the year
ended 31 July 2016.
Loss on sale of equipment R3 250
Depreciation for the year R164 400
Interest on loan R110 000
Income tax R518 000
Net income before taxation R1 223 000
2. Extract from the Statement of Financial Position (Balance Sheet) as at:
31 July 2016 31 July 2015
Fixed Assets: 7 332 850 5 170 000
Land and buildings 6 100 000 4 220 000
Equipment at carrying value 1 232 850 950 000
Equity 5 865 750 5 690 000
Share capital ? 4 655 000
Retained income ? 1 035 000
Long-term liabilities 987 250 900 000
Mortgage loan: RFS Financial Bank (12% p.a.) 987 250 900 000
IEB Copyright © 2016
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – INFORMATION BOOKLET Page vii of ix
3. Extract from the notes to the Financial Statements as at 31 July 2016
Note 5: Trade and other receivables
31 July 2016 31 July 2015
SARS – Income tax R22 700 ?
Note 6: Cash and cash equivalents
31 July 2016 31 July 2015
Bank R12 500
Petty cash R2 000 R1 500
Note 7: Trade and other payables
31 July 2016 31 July 2015
SARS – Income tax ?
Shareholders for dividends R113 000 R162 000
Bank ?
4. Additional information:
• The total dividends paid and declared for the year amounted to R338 000.
• The cash flow statement on 31 July 2016 reflected taxation paid of R557 050.
• The business bought new equipment during the year.
• They also disposed of obsolete equipment on 31 March 2016. The following
information relating to the disposal of this equipment was taken from the tangible asset
register:
Cost price of the equipment R180 000
Accumulated depreciation (1 August 2015) R87 500
Depreciation was calculated at 15% p.a. on the diminishing balance method.
• The business built an additional warehouse during the year.
• Claxton LTD had 931 000 ordinary shares in issue on 1 August 2015.
• On 1 August 2015, Claxton LTD decided to repurchase 50 000 ordinary shares from a
shareholder at R5,50 per share. The weighted average price per share on this date was
R5.
• During the financial year ended 31 July 2016, they issued further shares to the public at
a price of R5,55 per share.
• Claxton LTD took out a new loan of R218 000 during the year. Interest is capitalised
and loan repayments (including interest for the year) were made during the year.
• The net change in cash and cash equivalents for the year ended 31 July 2016 was
R119 000 (positive).
IEB Copyright © 2016 PLEASE TURN OVER
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – INFORMATION BOOKLET Page viii of ix
QUESTION 4 MANUFACTURING (48 marks, 29 minutes)
This question consists of 2 parts; each is related to a completely different business.
PART A
Information relating to Thorndon Manufacturers
Thorndon Manufacturers are a medium-sized business that specialises in the production of security
alarms. They supply their products to various security companies, but also have an online store
where they have a call centre selling security alarms directly from the factory. 90% of all the
selling and distribution costs are incurred by the online call centre.
1. The following balances were found in the stock accounts:
30 September 2016 1 October 2015
Raw materials stock R70 000 R55 000
Indirect materials stock R2 730 R4 500
Work-in-progress stock ? R65 050
Finished goods stock R80 500 R101 450
2. Raw materials were purchased during the year, R1 135 000. The owner returned raw
materials costing R2 500 that he had previously taken for his own personal use. The return
of this stock has not been recorded.
3. A credit invoice for R3 500 had not yet been recorded. This was in respect of transporting
raw materials from the harbour to the factory.
4. After the creditor's reconciliation had been completed, it was discovered that a bulk
purchase discount of R6 000 on raw materials had not been granted. Thornton
Manufacturers is entitled to this discount.
5. Sales for the year were R6 282 375. (30% of these sales are through the call centre.) Cost of
sales for the year were R2 512 950.
6. Indirect material bought during the year was R260 000. Indirect material used is divided
between the factory, administration, and selling and distribution in the ratio of 1 : 1 : 3.
7. At the end of the year it was discovered that indirect material in the factory (packing boxes)
costing R1 750 had been stolen. The stock is insured and the insurance will pay out R1 130
in October 2016. No entries have been made to record this theft.
8. Monthly insurance has remained constant for the last two years. Insurance paid for the year
amounted to R121 520 and this included insurance paid in advance for October and
November 2016. Insurance of R59 520 was allocated to selling and distribution, and R7 440
to administration.
9. R490 000 is the total rent. 60% is for the factory, 5% for administration and the rest is for
selling and distribution.
IEB Copyright © 2016
Downloaded from hlayiso.com
NATIONAL SENIOR CERTIFICATE: ACCOUNTING: PAPER I – INFORMATION BOOKLET Page ix of ix
10. The following salary and wage expenses were incurred:
Gross salaries
Contributions
and wages
Indirect labour Medical aid UIF
Factory R312 850 R7 002 R2 428
Administration R80 000 R1 650 R1 600
Direct labour, including contributions, amounts to R790 000.
11. Transport costs to deliver alarms to online customers were R35 080.
12. Total selling and distribution costs as a percentage of sales for the year was 16%.
PART B
Information relating to Bags of Fun
Bags of Fun is a small manufacturing business that produces transparent pencil bags. This business
supplies these pencil bags to various school shops in the Durban area. Maria Martins, the owner, is
concerned about the profitability and sustainability of her business.
The following information was taken from the books of Bags of Fun at their year-end,
31 October 2016.
Every year they sell all the goods they produced:
31 October
31 October 2016
2015
Total costs Unit cost Fixed/Variable
Direct materials costs R607 750 R5,50
Direct labour costs R508 300 R4,60
Selling and distribution costs R182 325 R1,65 All variable
Factory overheads cost R548 410 All Fixed
Administration costs R247 500 All Fixed
Selling price per unit R18,85 R15
31 October 31 October
2016 2015
Units produced and sold ? 98 000 units
Break-even point ? 78 000 units
IEB Copyright © 2016
Study this subject
Revise the topics in this paper, then practise them question by question.
- Grade 12 Accounting notes
CAPS revision notes with worked examples.
- Accounting questions by topic
Past exam questions sorted by CAPS topic, with memos where available.
- Grade 12 Accounting quizzes
Short topic quizzes with instant feedback.
- All Grade 12 Accounting past papers
Past papers by year, with memos where available.
- Grade 12 IEB past papers
More Accounting and other subjects in this collection.
Recommended for this subject
More papers and memos for this grade and subject.
Information sheetIEB
Accounting Grade 12 IEB 2019 Information Sheet (Afrikaans)
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2019 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB P1 2019 Information Sheet (Afrikaans)
Information sheetIEB
Accounting Grade 12 IEB Paper 2 2019 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB P2 2019 Information Sheet (Afrikaans)
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2018 Information Sheet
Related documents
Question paperIEB
Accounting Grade 12 IEB Paper 1 2016 Question Paper
MemorandumIEB
Accounting Grade 12 IEB Paper 1 2016 Memo
Information sheetIEB
Accounting Grade 12 IEB Paper 2 2016 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2018 Information Sheet
Information sheetIEB
Accounting Grade 12 IEB Paper 1 2017 Information Sheet
MemorandumIEB
Accounting Grade 12 IEB Paper 2 2016 Memo
More from Grade 12 Accounting
Question paperIEB
Accounting Grade 12 IEB Paper 1 2019 Question Paper
Question paperIEB
Accounting Grade 12 IEB Paper 1 2019 Question Paper (Afrikaans)
Question paperIEB
Accounting Grade 12 IEB Paper 2 2019 Question Paper
Question paperIEB
Accounting Grade 12 IEB Paper 2 2019 Question Paper (Afrikaans)
Question paperIEB
Accounting Grade 12 IEB Paper 1 2018 Question Paper
MemorandumIEB